Senior Content Editor
Director
Economic turbulence in recent years; such as unstable interest rates, soaring inflation, and a relentless cost-of-living crisis, has left household budgets stretched to their absolute limits. Unsurprisingly, this has led to a significant rise in adverse credit. From missed utility payments to defaults and CCJs, we’re seeing an increase in prospective borrowers with less than perfect credit files.
For mortgage brokers, this presents both a challenge and a huge opportunity. These leads aren't necessarily a lost cause, they are simply complex cases. Handling these enquiries with empathy and navigating the specialist lending market effectively, can secure you a client for life.
The mindset of the rejected customer
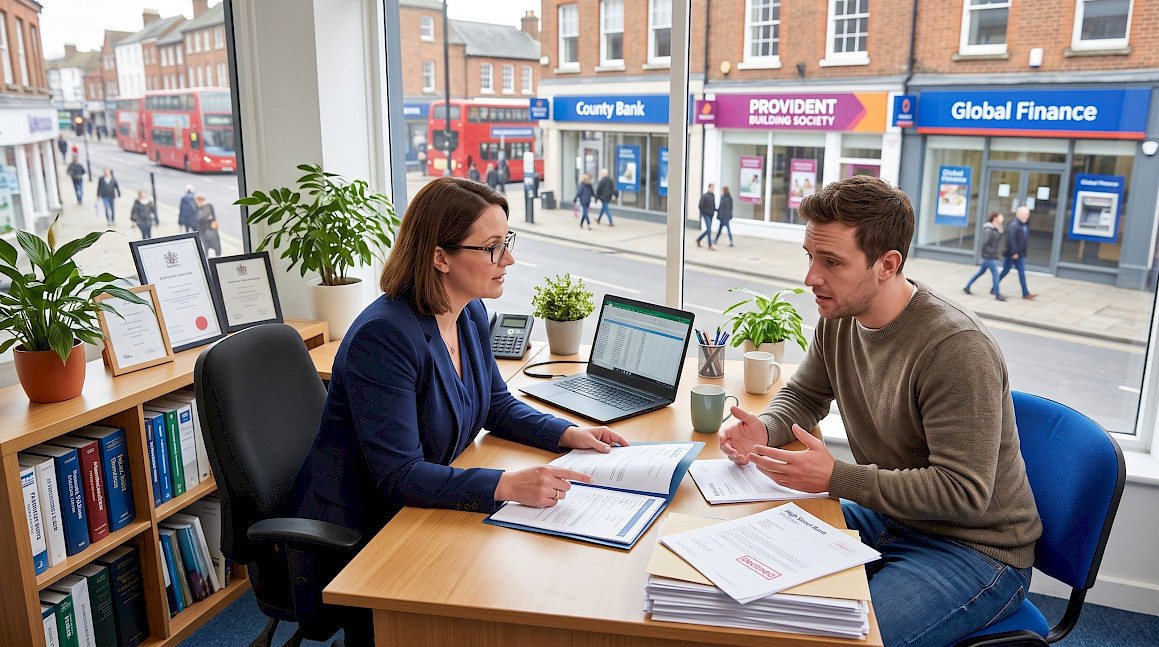
When a lead comes to you after being declined by a high street bank, they may feel embarrassed, defensive, or entirely hopeless about their property dreams.
If your first interaction feels like an interrogation or a repeat of their negative banking experience, it’s unlikely you’ll succeed. To successfully convert these leads, you’ll need to be a clear alternative to the bank, a trusted, non-judgemental adviser.
Here are four practical tips for converting adverse credit leads who have been turned away elsewhere.
1. Lead with empathy
Your primary goal in the first five minutes of the conversation is to de-escalate their anxiety and remove the stigma surrounding bad credit. If you normalise their circumstances, they are far more likely to let their guard down.
Many clients believe a default or CCJ makes them a financial pariah. So here’s your chance to reassure them otherwise. Explain how in today's economic climate, credit blips are incredibly common and far from the end of the road. Perhaps use a recent, anonymised example.
Emphasising that banks rely on automated pass or fail assessment algorithms, rather than looking at the application in person, is why they were declined. Tell them that specialist lenders use human underwriters, who consider the real life circumstances behind the credit score.
2. Uncover the full picture
To place an adverse case, you need meticulous detail, but without interrogating your client. Instead of asking them to remember exactly when a default was registered or the exact value of a CCJ, task them to download a credit report.
This allows you to view it for them, saving them from repeating their financial indiscretions. Once you have the report in hand, you can ask clarifying questions about specific events in a supportive, fact-finding manner, rather than making them feel like they are under a spotlight.
3. Recommend ‘stepping stone' mortgages
Adverse credit leads are often completely unaware of the specialist lending market. They assume that if their own bank said no, the whole market is closed to them.
Take the time to explain how specialist lenders operate, but be sure to manage expectations regarding interest rates. Specialist rates can induce 'rate shock' which can dissuade them from continuing, often citing the high cost of repayments.
However, this can easily be reframed as a stepping stone mortgage. Taking the permanence away from the less appealing higher rate products can be enough for some. If not, explaining that repaying their higher rate mortgage on time for a short fixed-term will help put them in a better position for lower rates in the future, usually swings the balance back in your favour.
Offer to contact them as soon as they become eligible for a lower rate remortgage, giving them a clear, optimistic roadmap for the future.
4. Set realistic timelines
As well as managing expectations with mortgage rates, it’s important to be open about the fact that complex cases tend to take longer to process. If a client is used to the promise of an instant decision in principle, they might interpret a few days of silence as an impending rejection.
Be transparent from day one. Let them know that manual underwriting takes time because the lender is taking the care to thoroughly review their individual circumstances. Keep communication frequent; even a quick email to tell them there is no update can go a long way towards preventing a nervous lead from abandoning the process.
Key Takeaways
-
In a volatile economy, the pool of clients with immaculate credit histories is shrinking, while the adverse credit market is growing rapidly
-
Brokers who refine their soft skills and learn to handle these cases with empathy, education, and transparency will find themselves with a highly lucrative and loyal client base
-
LeadCrowd provides a fully-stocked marketplace of financial services leads, including adverse mortgage enquiries. You can target by location, set your criteria, and start converting today - sign up now!